How to Compare Home Purchase Offers Beyond the Price: A Wisconsin Seller's Guide
EDUCATE 2 OWN | WISCONSIN SELLER EDUCATION
How to Compare Home Purchase Offers Beyond the Price
A Wisconsin Seller's Guide to Understanding Offers, Contingencies, and Net Proceeds
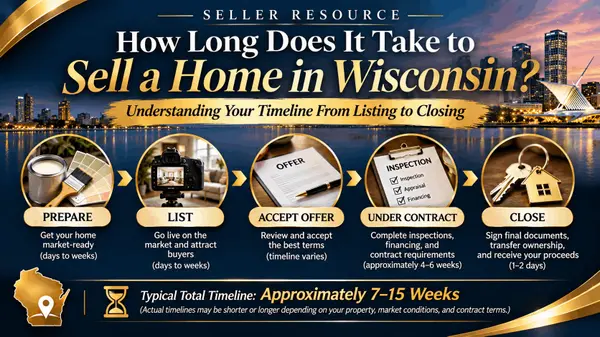
You've prepared your home, completed the photography, welcomed potential buyers, and officially placed your property on the market.
Now the moment you've been waiting for has arrived.
You received an offer!
Maybe you received one offer. Perhaps several buyers are interested in purchasing your home.
Naturally, your first instinct may be to look at the purchase price.
After all, wouldn't the buyer offering the most money automatically be the best choice?
Not necessarily.
An offer contains much more than a purchase price.
Financing, inspections, seller concessions, earnest money, appraisal provisions, closing dates, and other contractual terms can all influence your experience and financial outcome.
At Educate 2 Own, we believe homeowners should understand every important part of an offer before making their decision.
Let's explore how Wisconsin sellers can compare purchase offers with greater confidence.
The highest offer is not automatically the strongest offer. Consider the complete purchase agreement, your estimated net proceeds, the buyer's ability to complete the transaction, and whether the proposed terms support your selling goals.
1. Start With the Purchase Price
The purchase price is the amount a buyer offers to pay for your property.
It is one of the most important parts of an offer, but it shouldn't be evaluated alone.
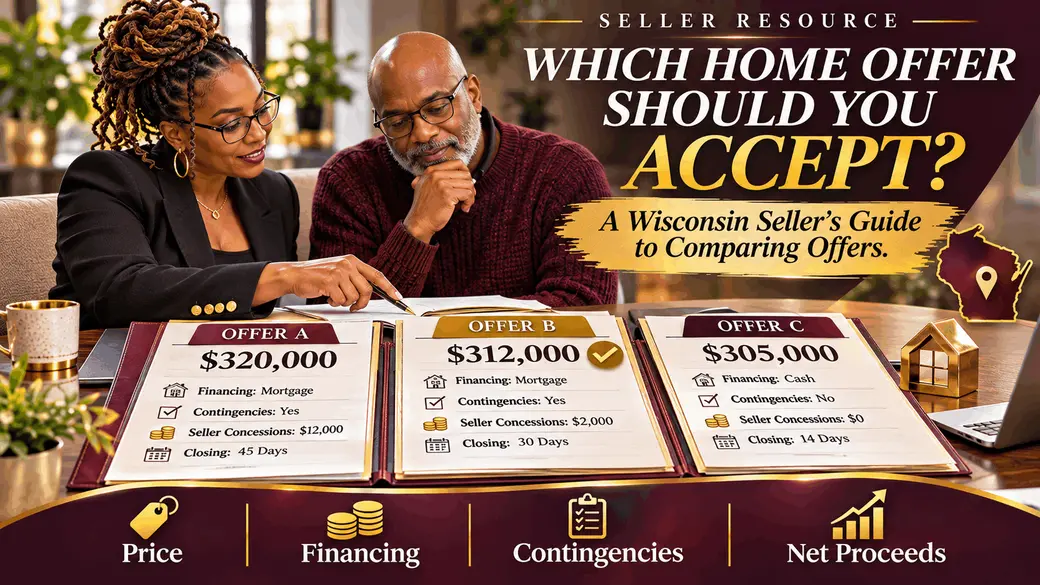
For example, imagine receiving two offers:
Buyer A: Offers $320,000
Buyer B: Offers $312,000
At first glance, Buyer A's offer appears better because it's $8,000 higher.
However, what if Buyer A also requests $12,000 in seller concessions?
Meanwhile, Buyer B requests only $2,000 in concessions.
Now the financial comparison changes.
This is why sellers should review more than the purchase price alone.
2. Understand Seller Concessions
Seller concessions are expenses the seller agrees to pay on behalf of the buyer as part of the transaction.
These may include contributions toward certain allowable buyer closing costs.
Depending on the transaction, a buyer may request assistance with expenses such as:
- Allowable lender fees
- Prepaid expenses
- Certain closing costs
- Other permitted transaction expenses
The amount and type of allowable concessions depend on the purchase agreement, financing program, and applicable requirements.
Seller concessions are negotiable.
A homeowner is not automatically required to agree to every requested concession.
However, concessions may help certain buyers complete their purchase.
A larger purchase price combined with substantial concessions may produce lower net proceeds than a slightly smaller offer.
3. Compare the Financial Impact of Each Offer
Let's return to our previous example.
Three buyers submit offers on the same Wisconsin home.
| Offer Details | Buyer A | Buyer B | Buyer C |
|---|---|---|---|
| Purchase Price | $320,000 | $312,000 | $305,000 |
| Requested Seller Concessions | $12,000 | $2,000 | $0 |
| Financing | Mortgage | Mortgage | Cash |
| Inspection Contingency | Yes | Yes | No |
| Price Less Concessions | $308,000 | $310,000 | $305,000 |
Although Buyer A submitted the highest purchase price, Buyer B offers $2,000 more after subtracting the requested concessions.
Buyer C has the lowest purchase price but is offering cash without an inspection contingency.
That may appeal to a seller who values certain terms or a shorter transaction timeline.
However, none of these offers is automatically the best choice.
Financing, appraisal requirements, contract deadlines, proof of funds, and the buyer's ability to close still matter.
Important: The amounts above are not complete seller net proceeds.
Mortgage payoffs, brokerage compensation, property taxes, title expenses, transfer fees, and other transaction costs would also need to be considered.
Actual concessions and their treatment must comply with applicable financing rules.
This example is hypothetical and does not represent actual purchase offers or guaranteed results.
4. Evaluate the Buyer's Financing
The buyer's financing can influence the transaction timeline and requirements.
Common purchase arrangements include:
Conventional Financing
Conventional mortgage financing generally involves lender underwriting, property valuation, and other eligibility requirements.
FHA Financing
FHA-insured financing has specific borrower and property eligibility requirements.
Certain property conditions may need attention before the loan can close.
VA Financing
VA-backed financing may be available to eligible veterans, service members, and other qualified borrowers.
VA loans have program-specific property and financing requirements.
Cash Purchases
A cash buyer intends to purchase without traditional mortgage financing.
However, sellers should review credible proof of available funds and any remaining contingencies.
No financing type automatically guarantees that a transaction will close successfully.
Seller Tip: Evaluate the buyer's documented qualifications, financing terms, and contractual requirements rather than relying on assumptions about a particular loan program.
5. Preapproval vs. Prequalification
Buyers may submit different types of lender documentation with their offers.
A prequalification may be based on preliminary financial information provided by the buyer.
A preapproval may involve a more detailed review of credit, income, assets, and other financial information.
However, lender practices and terminology vary.
Neither prequalification nor preapproval guarantees final loan approval.
A buyer's lender may still need to complete underwriting, property evaluation, and other requirements.
When reviewing a financed offer, consider the available lender documentation and the terms of the financing contingency.
6. Understand Earnest Money
Earnest money is an amount a buyer may provide as part of the purchase transaction.
The accepted Wisconsin purchase agreement typically addresses:
- The amount of earnest money
- When it must be delivered
- Who will hold the funds
- How it will be credited at closing
- Applicable procedures if the transaction does not close
A larger earnest money deposit may demonstrate a greater financial commitment.
However, it does not automatically make an offer risk-free.
Earnest money is not automatically forfeited to the seller if a buyer fails to close.
Its disposition depends on the contract, the circumstances, and applicable law.
7. Pay Attention to Inspection Contingencies
A home inspection contingency can give the buyer certain rights to inspect the property within an agreed period.
The specific language of the accepted Wisconsin offer determines how the contingency operates.
Inspection provisions may address:
- Inspection deadlines
- Access to the property
- Notice of Defects procedures
- Seller right-to-cure provisions
- Other agreed contractual requirements
A buyer who does not include an inspection contingency may be offering different contractual terms.
However, waiving an inspection contingency does not eliminate every possible legal or contractual issue.
Important: A proposed amendment requesting repairs is not the same as a formal Notice of Defects.
Wisconsin sellers should carefully review the applicable contract provisions and deadlines.
8. What About Appraisal Requirements?
When a buyer is obtaining mortgage financing, the lender may require an appraisal.
An appraisal provides an opinion of the property's value for lending purposes.
If the appraised value is lower than the purchase price, additional decisions may be required.
Depending on the contract, possible outcomes may include:
- The buyer providing additional funds
- The parties negotiating a different purchase price
- Reviewing permitted appraisal reconsideration options
- Exploring another financing arrangement
- Following applicable contract provisions
A buyer offering significantly more than recent comparable sales may create additional valuation considerations.
However, a high purchase price does not automatically mean the property will appraise below the contract price.
The actual appraisal and purchase agreement determine the available options.
9. Compare Closing Dates
The proposed closing date can be especially important when selling your home.
Perhaps you're relocating for employment.
Maybe you're purchasing another property and need the proceeds from your current sale.
Or you may need additional time to coordinate your move.
When comparing offers, ask:
- Does the proposed closing date work for me?
- Will I need temporary housing?
- Am I purchasing another home?
- Will I have overlapping mortgage or housing expenses?
- Could a delayed closing affect another obligation?
- What happens if the buyer cannot close on time?
A slightly lower offer with a closing date that supports your plans may be more practical than a higher offer with inconvenient terms.
Closing dates are negotiated terms, not guaranteed outcomes.
10. Understand Possession Arrangements
Closing and possession are related, but they are not always the same event.
The purchase agreement should establish when the buyer is entitled to possession of the property.
Some sellers may request additional time to move after the transaction closes.
Depending on the circumstances, the parties may negotiate an appropriate post-closing occupancy arrangement.
Such arrangements should address relevant issues, including:
- Possession date
- Occupancy charges, if any
- Insurance considerations
- Utility responsibilities
- Property condition obligations
- Consequences of delayed possession
Any arrangement should be properly documented.
11. What If the Buyer Needs to Sell Another Home?
Some buyers need to sell an existing property before completing their next purchase.
These offers may include a contingency related to the closing of the buyer's property.
This can create additional considerations for the seller.
For example:
- Is the buyer's existing property already under contract?
- What deadlines apply?
- What happens if the other sale does not close?
- Does the purchase agreement include secondary-offer provisions?
- How might the contingency affect your moving plans?
A contingent offer is not automatically a poor offer.
However, sellers should understand the added dependencies before accepting.
The applicable Wisconsin purchase agreement determines the parties' rights and obligations.
12. Are Buyers Asking You to Pay Their Brokerage Compensation?
Depending on the purchase offer, a buyer may request that the seller pay an agreed amount toward the buyer's brokerage compensation.
Real estate brokerage compensation is negotiable and is not established by law.
Sellers are not automatically required to pay the buyer's brokerage compensation.
However, they may agree to a negotiated payment as part of the overall purchase transaction.
The applicable brokerage agreements, purchase contract, and legal requirements determine how such payments are documented and handled.
When comparing offers, consider any requested seller-paid brokerage compensation along with other expenses.
Avoid double-counting amounts already reflected in your brokerage compensation obligations or seller net sheet.
Seller Tip: Ask for a clear explanation of who is receiving compensation, who is responsible for paying it, and how it affects your estimated proceeds.
13. Should You Accept the First Offer?
There is no universal rule requiring a homeowner to accept the first offer they receive.
A seller may choose to accept, reject, or counter an offer.
However, the seller should consider the offer's expiration or binding-acceptance deadline.
Waiting for another buyer involves risk.
The original buyer may withdraw an offer before binding acceptance, subject to applicable contract requirements.
Likewise, another offer may never arrive.
The decision should reflect the seller's goals, market conditions, and the terms currently available.
14. What Happens When You Receive Multiple Offers?
Receiving multiple offers can create opportunities, but it can also make the decision more complicated.
Each offer should be reviewed according to its complete terms.
Possible considerations include:
- Purchase price
- Buyer financing
- Requested seller concessions
- Earnest money
- Inspection contingencies
- Financing contingencies
- Appraisal-related provisions
- Closing date
- Possession arrangements
- Other contractual requirements
A seller may consider negotiating with one or more buyers, subject to applicable laws, contractual duties, and brokerage obligations.
A seller should not assume every buyer will be willing to improve their original offer.
Once an offer reaches binding acceptance, the parties have contractual obligations.
Receiving a better offer afterward does not automatically give the seller the right to cancel the first agreement.
15. Use an Offer Comparison Worksheet
When reviewing multiple offers, organizing the information can make the decision easier.
Rather than trying to remember every detail from several contracts, consider a side-by-side comparison.
Wisconsin Seller Offer Comparison Checklist
Review these items before making your decision.
- ☐ Compare purchase prices
- ☐ Review requested seller concessions
- ☐ Identify any requested brokerage compensation payments
- ☐ Review buyer financing arrangements
- ☐ Examine available lender documentation or proof of funds
- ☐ Compare earnest money deposits
- ☐ Review inspection contingencies
- ☐ Evaluate appraisal-related provisions
- ☐ Review financing contingency deadlines
- ☐ Identify home sale or closing contingencies
- ☐ Compare closing dates
- ☐ Review possession arrangements
- ☐ Identify included and excluded property
- ☐ Review other contractual obligations
- ☐ Compare estimated seller net proceeds
- ☐ Consider the buyer's ability to complete the transaction
- ☐ Evaluate how each offer supports your goals
This checklist is intended for general educational purposes and does not replace reviewing the actual purchase agreement.
16. Which Offer Is Really the Best?
The answer depends on your priorities and the complete terms available.
For one homeowner, the primary goal may be maximizing net proceeds.
For another, the timing of the sale may be more important.
Someone selling an inherited property might prioritize minimizing repairs and maintenance.
A homeowner purchasing another property may care most about coordinating both transactions.
The strongest offer is the one that best aligns with your goals after considering the financial terms, contractual obligations, and transaction risks.
There is no one-size-fits-all answer.
Frequently Asked Questions
Should I always accept the highest offer?
Not necessarily.
Consider seller concessions, financing requirements, contingencies, closing dates, estimated net proceeds, and the buyer's ability to complete the transaction.
Is a cash offer better than a financed offer?
Not automatically.
Cash offers may eliminate traditional mortgage financing requirements, but cash buyers can still include contractual contingencies.
Review the entire offer rather than assuming one financing method is always better.
Does more earnest money mean a stronger offer?
It may indicate a greater financial commitment, but earnest money alone does not guarantee a successful closing.
Can I negotiate seller concessions?
Yes.
Seller concessions are negotiable, subject to applicable financing and contract requirements.
Can I counter an offer?
Yes.
Sellers may propose different terms through an appropriate counteroffer.
A counteroffer can affect the status of the original offer, so review the legal and contractual implications before proceeding.
Can I accept two offers on the same house?
Wisconsin transactions may involve primary and secondary offers.
However, accepting a secondary offer does not automatically release the seller from an existing primary purchase agreement.
Proper contract language and procedures matter.
Can a seller change their mind after accepting an offer?
An accepted purchase agreement creates legal obligations.
A seller generally cannot simply cancel because another buyer offers more money.
Available rights depend on the contract and applicable law.
What if an offer is above asking price?
An above-asking-price offer may be attractive, but sellers should still evaluate financing, appraisal considerations, concessions, and other terms.
Who decides which offer to accept?
The seller makes the decision, subject to applicable legal and contractual requirements.
A real estate professional can help explain the available offers and potential implications.
The Best Offer Is About More Than the Price
Your home may be one of your largest financial assets.
Understanding the terms of a purchase offer can help you protect your interests, evaluate potential proceeds, and prepare for your next chapter.
At Educate 2 Own, we believe homeowners deserve clear information and personalized guidance before making important real estate decisions.
Whether you're selling a single-family home, duplex, condominium, or investment property, our approach begins with education.
Serving Milwaukee, Wauwatosa, West Allis, Brookfield, Glendale, and communities throughout Wisconsin.
Explore Your Property's ValueAdditional Resources
- NAR: Navigating Multiple Offers
- NAR: Understanding Seller Concessions
- Wisconsin REALTORS Association: Real Estate Form Updates
Educate. Empower. Own. Thrive!
Stephanie Stuart, REALTOR®
Educate 2 Own | Brokered by Epique Realty
educate2own.com
Disclaimer: This article provides general educational information and is not legal, tax, financial, lending, or appraisal advice. Purchase agreements, financing requirements, transaction costs, and contractual rights vary. Examples are hypothetical and do not guarantee a particular outcome. Consult appropriate qualified professionals regarding your circumstances.
Categories
Recent Posts