What Happens After You Accept an Offer on Your Wisconsin Home?
EDUCATE 2 OWN | WISCONSIN SELLER EDUCATION
What Happens After You Accept an Offer on Your Wisconsin Home?
Your Step-by-Step Guide From Accepted Offer to Closing Day
Congratulations! You've accepted an offer on your home.
After preparing your property, marketing it, welcoming potential buyers, and reviewing offers, reaching an agreement is an exciting milestone.
But there's something important every Wisconsin home seller should understand:
An accepted offer does not mean the sale is complete.
There are still several steps between accepting a purchase offer and officially transferring ownership of your property.
Depending on the agreement, these steps may include home inspections, financing approval, appraisal, title work, and preparing for closing.
At Educate 2 Own, we believe sellers should understand what's happening throughout the transaction, not simply wait for updates.
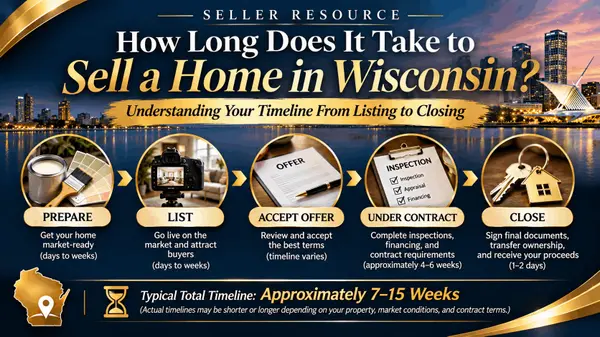
Here's what you can generally expect after accepting an offer on your Wisconsin home.
Every transaction is different. The accepted purchase contract determines important deadlines, responsibilities, contingencies, and closing terms. Always follow your specific agreement rather than assuming every home sale works the same way.
1. Your Home Is Now Under Contract
Once the parties have reached binding acceptance, the property is considered under contract.
This means the buyer and seller have entered into a legally binding purchase agreement.
The agreement outlines important details, which may include:
- Purchase price
- Earnest money requirements
- Inspection contingency deadlines
- Financing requirements
- Appraisal-related provisions
- Closing date
- Included and excluded property
- Possession arrangements
- Other negotiated conditions
Your real estate professional can help you understand the transaction timeline and identify upcoming responsibilities.
Seller Tip: Keep a copy of the accepted offer and any amendments in an accessible location throughout the sale.
2. Earnest Money Is Delivered
Earnest money is money a buyer may provide as part of the purchase transaction.
It can demonstrate the buyer's intention to proceed under the agreed contract terms.
In Wisconsin, earnest money is generally handled according to the accepted offer and applicable trust account requirements.
The purchase agreement typically identifies:
- How much earnest money is required
- When it must be delivered
- Who will hold the funds
- How the funds will be handled at closing
Earnest money is not automatically paid directly to the seller when the offer is accepted.
If the transaction closes, the funds are generally credited toward the buyer's purchase obligations.
If the transaction does not close, the disposition of earnest money depends on the contract, applicable law, and the circumstances.
3. The Buyer May Schedule a Home Inspection
If the accepted offer includes an inspection contingency, the buyer may arrange a home inspection within the contractual deadline.
A qualified home inspector evaluates accessible property components and reports observations about their condition.
Common areas of evaluation may include:
- Roof and exterior
- Foundation and structure
- Electrical systems
- Plumbing systems
- Heating and cooling equipment
- Attic and insulation
- Basement and visible moisture concerns
- Other accessible components
The inspection does not automatically require the seller to repair everything identified in the report.
What happens next depends on the inspection contingency and the parties' agreement.
Seller Tip: Make sure the inspector can access the areas covered by the inspection.
4. What Happens If the Inspection Finds Problems?
Most properties have some degree of wear, maintenance needs, or age-related conditions.
An inspection report may identify concerns ranging from minor maintenance items to significant defects.
Depending on the accepted offer, the buyer may:
- Proceed without requesting changes
- Propose an amendment involving repairs or credits
- Deliver a Notice of Defects if permitted by the contingency
- Request additional evaluation when authorized
In Wisconsin, an important distinction exists between a proposed amendment and a formal Notice of Defects.
Proposed Amendment
An amendment is a proposed change to the purchase agreement.
For example, a buyer might request that the seller repair a roof or provide a negotiated credit.
The seller may agree, reject the proposal, or negotiate different terms.
Until the parties reach an agreement, the original contract terms remain in effect.
Notice of Defects
A Notice of Defects is a formal contractual notice used under an applicable inspection contingency.
Depending on the terms of the offer, proper delivery may trigger the seller's right-to-cure provisions or other contractual consequences.
Important: A proposed amendment is not the same as a Notice of Defects.
Negotiating an amendment does not automatically extend the inspection contingency deadline.
Because these documents can affect the parties' contractual rights, review them promptly with your real estate professional or qualified legal adviser.
Inspection deadlines matter. Don't assume that negotiations, text messages, or verbal discussions automatically change the terms of your purchase contract. Any required contractual changes should be properly documented.
5. The Property May Be Appraised
When a buyer is purchasing a home with mortgage financing, the lender may require an appraisal.
An appraisal provides an independent opinion of the property's value for the lender's purposes.
The appraiser may consider:
- Recent comparable sales
- Property size and characteristics
- Overall condition
- Location and market conditions
- Other relevant factors
An appraisal is different from a home inspection.
An inspection generally focuses on property condition, while an appraisal focuses on value.
What If the Appraisal Comes in Low?
If the appraised value is below the purchase price, the buyer's lender may not approve financing based on the original terms.
Depending on the contract, financing arrangements, and the parties' willingness to negotiate, possible responses may include:
- The buyer contributing additional funds
- The parties negotiating a different price
- Reviewing whether an appraisal reconsideration is appropriate
- Exploring another permitted financing solution
- Following applicable contractual provisions
A low appraisal does not automatically mean the seller must reduce the price.
The parties' rights and options depend on their agreement.
6. The Buyer's Financing Is Finalized
If the buyer is obtaining a mortgage, the lender generally continues reviewing the loan application after the offer is accepted.
This process is commonly called underwriting.
The lender may verify:
- Income and employment
- Credit information
- Assets and available funds
- Existing debts
- Appraisal and property requirements
- Other loan program conditions
A buyer's preapproval is not a guarantee that the loan will receive final approval.
If the offer contains a financing contingency, the parties must follow the specific contractual requirements and deadlines.
Some transactions may experience delays if additional documentation, property-related repairs, or financing changes are required.
7. The Title Company Reviews Ownership
Before closing, the title or settlement provider generally reviews records related to the property's ownership.
This process helps identify matters that may need to be addressed before the property is transferred.
Examples include:
- Existing mortgages
- Recorded liens
- Judgments affecting title
- Ownership discrepancies
- Recorded easements
- Other title-related concerns
Some issues are resolved through routine closing procedures.
Others may require additional documents, payments, or legal assistance.
Seller Tip: If your property is part of an estate, trust, divorce, or other ownership arrangement, discuss documentation requirements early.
8. Your Mortgage Payoff Is Requested
If you have a mortgage, the closing provider generally obtains the information needed to satisfy the loan at closing.
Your mortgage payoff amount may differ from the balance shown on your monthly statement.
The final payoff may include accrued interest and other applicable charges.
If your property has a home equity loan, second mortgage, or other lien, additional payoff information may also be required.
These amounts affect your final proceeds from the sale.
9. Review Your Estimated Seller Net Proceeds
Before closing, you should have an opportunity to review your anticipated sale proceeds.
The final amount depends on the purchase price and applicable expenses.
These may include:
- Mortgage payoff
- Negotiated brokerage compensation
- Property tax prorations
- Applicable Wisconsin transfer fees
- Title and settlement charges
- Agreed seller concessions
- Other applicable transaction expenses
A seller net sheet can provide an estimate before closing.
The final settlement statement will reflect the applicable transaction figures.
10. Prepare for the Buyer's Final Walkthrough
Depending on the purchase agreement, the buyer may have the right to conduct a walkthrough before closing.
The purpose is generally to confirm the property's condition and review applicable contractual obligations.
Before the walkthrough, consider:
- Completing agreed repairs
- Removing belongings as required by the contract
- Leaving included fixtures and appliances in place
- Maintaining agreed property conditions
- Ensuring access to relevant areas
- Preparing keys and access devices
The walkthrough is not automatically an opportunity to renegotiate every property condition.
The parties' rights depend on the purchase agreement and applicable circumstances.
11. Review Closing Documents
As the closing date approaches, the settlement provider prepares the documentation needed to complete the sale.
Sellers may be asked to review or sign:
- Settlement statements
- Deed and transfer documents
- Mortgage payoff authorizations
- Tax-related forms
- Other transaction-specific documents
Review your personal information, property details, financial figures, and instructions carefully.
The buyer's lender generally provides a Closing Disclosure to the buyer at least three business days before closing when federal mortgage disclosure requirements apply.
That buyer disclosure requirement should not be confused with the seller's settlement statement.
If you notice an error, contact the appropriate closing professional before signing.
12. Closing Day: The Property Changes Hands
Closing is the final stage of the real estate transaction.
The process may include:
- Signing required documents
- Completing the buyer's funding requirements
- Paying applicable transaction expenses
- Satisfying existing mortgages or liens
- Coordinating deed recording
- Completing possession arrangements
The specific sequence varies depending on the transaction, lender, and settlement provider.
Once the transaction has been properly completed, ownership is transferred according to the applicable legal requirements.
13. When Will You Receive Your Money?
One of the most common questions sellers ask is:
"When do I get paid?"
Seller proceeds are generally disbursed after the applicable closing and funding requirements have been satisfied.
Depending on the transaction and settlement provider, payment may be arranged through a wire transfer or another approved method.
The timing of funds becoming available can vary.
Always confirm disbursement instructions and expected availability with your closing professional.
Real estate transactions can be targeted by wire fraud. Never rely solely on emailed instructions for sending money or changing banking information. Verify sensitive instructions using a trusted, independently confirmed telephone number.
14. What If Something Goes Wrong Before Closing?
Not every accepted offer results in a completed sale.
Potential complications include:
- Inspection-related disagreements
- Financing difficulties
- Appraisal concerns
- Title problems
- Missed contractual deadlines
- Disagreements involving possession or repairs
If a problem arises, the appropriate response depends on the contract and the circumstances.
Possible next steps may include negotiating an amendment, resolving a contractual issue, or obtaining legal advice.
Do not assume either party can automatically cancel the transaction without consequences.
Your accepted offer determines important rights and obligations.
15. What Should You Do While Waiting for Closing?
While the buyer completes their transaction requirements, you can prepare for your move.
Consider:
- Organizing moving arrangements
- Scheduling utility changes
- Updating your mailing address
- Gathering warranties and appliance manuals
- Coordinating property access
- Confirming agreed repairs are completed
- Reviewing final financial arrangements
- Preparing keys and garage access devices
- Planning for the agreed possession date
Avoid making assumptions about the closing or possession date until the applicable requirements are satisfied.
Your Wisconsin Seller Under-Contract Checklist
Use this checklist to stay organized between accepting an offer and closing day.
- ☐ Save your accepted purchase agreement
- ☐ Review all important contract deadlines
- ☐ Confirm earnest money arrangements
- ☐ Coordinate inspection access when applicable
- ☐ Review inspection notices and amendments promptly
- ☐ Monitor financing and appraisal milestones
- ☐ Provide requested title information
- ☐ Confirm mortgage payoff arrangements
- ☐ Review estimated net proceeds
- ☐ Complete agreed property repairs
- ☐ Prepare for the final walkthrough
- ☐ Review closing documents
- ☐ Confirm moving and possession arrangements
- ☐ Verify proceeds disbursement instructions
Your exact responsibilities depend on the accepted purchase agreement and your individual transaction.
Frequently Asked Questions
Can the buyer back out after accepting an offer?
Possibly, depending on the contractual contingencies, deadlines, and circumstances.
A buyer does not automatically have an unrestricted right to cancel without consequences.
Does the seller have to fix everything found during inspection?
No. Repair obligations depend on the purchase agreement and any subsequent agreements between the parties.
Can the seller accept another offer while under contract?
A seller may be able to consider a secondary offer, depending on the circumstances and contractual obligations.
However, a secondary offer does not automatically release the seller from the first accepted agreement.
What happens if the buyer's financing falls through?
The result depends on the financing contingency, other contractual provisions, and whether the parties have met their obligations.
Do I have to move out before closing?
Not necessarily. Your possession obligations depend on the accepted purchase agreement.
Confirm when the property must be vacated and when the buyer is entitled to possession.
Will I receive my money on closing day?
Funds are disbursed according to applicable closing and funding requirements.
Confirm expected timing with the settlement provider.
From Accepted Offer to Your Next Chapter
Selling a home involves more than finding a buyer. Understanding the process can help you feel prepared from the first offer through closing day.
At Educate 2 Own, we help Wisconsin homeowners understand their options, navigate the selling process, and make informed decisions about their real estate goals.
Whether you're considering selling soon or simply planning for the future, education is a great place to begin.
Explore Your Property's ValueEducate. Empower. Own. Thrive!
Stephanie Stuart, REALTOR®
Educate 2 Own | Brokered by Epique Realty
educate2own.com
Disclaimer: This article provides general educational information and does not constitute legal, tax, lending, or financial advice. Contract terms, inspection procedures, disclosure requirements, financing, and closing practices vary. Consult qualified professionals regarding your individual transaction.
Categories
Recent Posts