Closing Costs in Wisconsin: What Homebuyers Need to Know Before Closing
EDUCATE 2 OWN | FIRST-TIME HOMEBUYER SERIES
You're Buying a House! But What Are Closing Costs?
You've found a home, received mortgage preapproval, and started planning your purchase.
You've probably heard about saving for a down payment. But did you know there are additional expenses associated with purchasing a home?
These expenses are commonly called closing costs.
Understanding closing costs before purchasing a home can help you budget responsibly, explore available assistance, and avoid unexpected financial stress.
Whether you're buying in Milwaukee, Wauwatosa, West Allis, Racine, Madison, Green Bay, or another Wisconsin community, let's break down what you should know.
1. What Are Closing Costs?
Closing costs are expenses associated with obtaining your mortgage, transferring property ownership, and completing your real estate transaction.
These expenses are generally separate from your down payment.
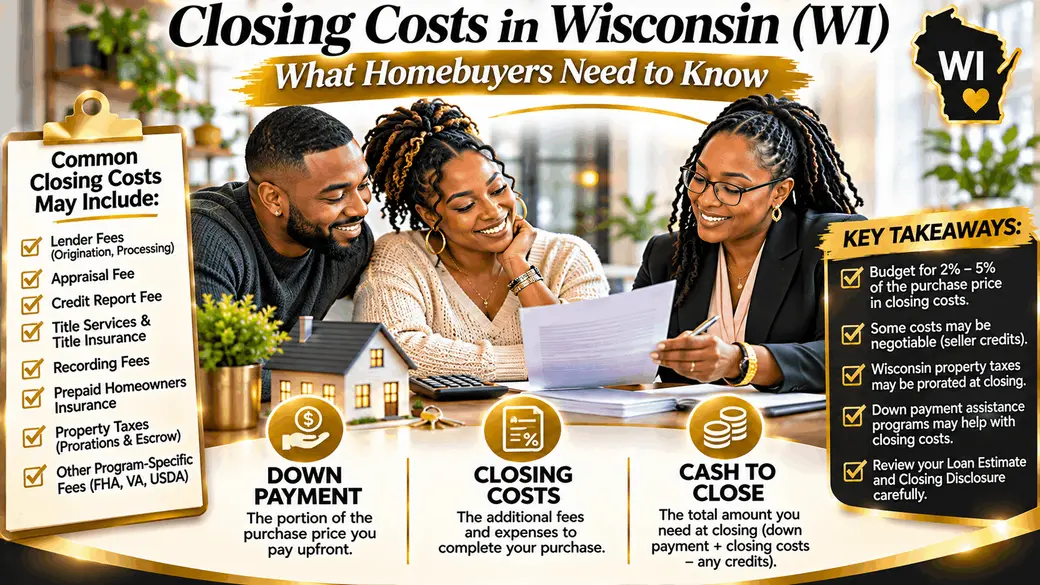
Depending on the transaction, closing costs may include:
- Mortgage lender fees
- Appraisal fees
- Credit reporting fees
- Title services and title insurance
- Property recording fees
- Prepaid homeowners insurance
- Prepaid mortgage interest
- Property tax and insurance escrow deposits
- Other applicable settlement expenses
Not every buyer pays the same fees.
The amount depends on factors such as the purchase price, mortgage program, lender, property location, and negotiated contract terms.
2. How Much Are Closing Costs in Wisconsin?
As a general planning estimate, closing costs often range from approximately 2% to 5% of a home's purchase price.
However, your actual costs may fall outside this range.
Example: Estimated Closing Costs
$150,000 Home
Estimated closing costs: $3,000–$7,500
$200,000 Home
Estimated closing costs: $4,000–$10,000
$250,000 Home
Estimated closing costs: $5,000–$12,500
$300,000 Home
Estimated closing costs: $6,000–$15,000
These estimates are for educational purposes and do not include the down payment.
Your lender can provide a more personalized estimate based on your financing and purchase details.
Don't wait until you find your dream home to ask about closing costs. Request an estimate from your lender before beginning your home search.
3. Closing Costs vs. Down Payment: What's the Difference?
Your down payment and closing costs serve different purposes.
Down Payment: The portion of the purchase price you contribute instead of borrowing through your mortgage.
Closing Costs: The additional expenses involved in completing the purchase and financing.
Example: Purchasing a $200,000 Home
Purchase Price: $200,000
Illustrative 3% Down Payment: $6,000
Illustrative Closing Costs: $6,000
Estimated Total: $12,000
This example assumes a mortgage program allowing a 3% down payment and estimated closing costs of 3%.
Actual requirements depend on your loan, transaction, and eligibility.
Seller credits, assistance programs, earnest money, and other adjustments may change the amount you need to bring to closing.
4. What Fees Does Your Mortgage Lender Charge?
Some closing costs are associated with obtaining your mortgage.
These may include:
Loan Origination Charges
Origination charges are fees associated with making or processing your mortgage.
Depending on the lender, these may include application, processing, underwriting, or origination fees.
Credit Reporting Fees
Lenders may charge fees for obtaining credit information used during mortgage underwriting.
Mortgage Discount Points
Discount points are optional upfront charges that may allow you to obtain a lower mortgage interest rate.
Paying points doesn't automatically make financial sense for every buyer.
Ask your lender to compare financing options with and without discount points.
Other Mortgage Program Fees
Certain mortgage programs have additional upfront charges.
For example, FHA financing generally includes an upfront mortgage insurance premium.
VA loans may include a funding fee unless the borrower qualifies for an exemption.
USDA guaranteed loans may include an upfront guarantee fee.
Some program fees may be eligible for financing rather than being paid entirely upfront.
Ask your lender which fees apply to your mortgage and how they affect your total borrowing costs.
5. What Are Title Fees and Title Insurance?
Title services are an important part of many real estate transactions.
A title company or other qualified professional may review public records to identify recorded ownership interests, liens, and other matters affecting the property.
Title-related expenses may include:
- Title searches
- Title insurance
- Closing or settlement services
- Document preparation or related services
What Is Title Insurance?
Title insurance provides protection against certain covered ownership and title-related risks, subject to the policy's terms and exclusions.
There are generally two types:
- Lender's Title Insurance: Protects the lender's insured interest.
- Owner's Title Insurance: Protects the owner's insured interest.
Which party pays particular title-related costs depends on the purchase agreement, lender requirements, and transaction arrangements.
Ask your closing professional to explain the coverage, fees, and responsibilities before closing.
6. Understanding Wisconsin Property Taxes at Closing
Wisconsin property taxes deserve special attention when budgeting for a home purchase.
Property taxes may be prorated between the buyer and seller at closing.
Proration means allocating an expense between the parties based on the agreed calculation and their respective periods of responsibility.
For example, a seller may provide a credit for the portion of property taxes attributed to their ownership period.
However, the exact calculation depends on the accepted purchase contract.
Why Does This Matter?
A property tax credit can affect the amount of money you need to bring to closing.
But that doesn't necessarily mean you won't have to pay property taxes later.
Depending on the transaction, you may be responsible for paying an upcoming tax bill or contributing funds toward a lender-managed escrow account.
Wisconsin's residential offer form includes provisions addressing property tax prorations and the method used to calculate them.
Important: The taxes shown in a listing or previous tax bill may not reflect what you'll pay in future years.
Changes in assessed values, municipal tax rates, exemptions, or property improvements may affect future taxes.
Ask your REALTOR® and lender to explain how property tax prorations, escrow deposits, and future tax bills could affect your closing costs and monthly mortgage payment.
7. What Is a Mortgage Escrow Account?
Many mortgage lenders collect money each month to help pay certain property-related expenses.
This money is held in an escrow account.
Escrow accounts commonly help pay:
- Property taxes
- Homeowners insurance
- Other eligible property-related charges
At closing, your lender may require an initial escrow deposit to establish the account.
The amount depends on your anticipated expenses, payment schedule, and applicable escrow requirements.
Escrow deposits are different from your down payment.
They also differ from prepaid expenses such as an upfront homeowners insurance premium.
Ask your lender how these amounts were calculated.
8. What Are Prepaid Expenses?
Some expenses must be paid before they would normally become due.
These are commonly called prepaid expenses.
Examples may include:
- Homeowners insurance premiums
- Mortgage interest covering the period between closing and the end of the month
- Other applicable prepaid charges
For example, your lender may require payment of your first year's homeowners insurance premium at closing.
Prepaid expenses are commonly included in the overall closing cost calculation.
However, the exact amounts depend on your property, mortgage, insurance arrangements, and closing date.
9. What About Wisconsin Recording and Transfer Fees?
Wisconsin real estate transactions may involve government recording and transfer fees.
Recording Fees
Recording fees are charged to record certain legal documents with the county Register of Deeds.
For example, the deed and mortgage may need to be recorded.
The applicable charges depend on the documents and recording requirements.
Real Estate Transfer Fee
Wisconsin generally imposes a real estate transfer fee on taxable conveyances.
The standard fee is $3 per $1,000 of value, with calculation rules established by state law.
Under Wisconsin law, the seller or grantor is generally responsible for the fee, although the purchase agreement may address how transfer-related costs are allocated.
Some transfers are exempt from the fee.
Buyers should review their purchase agreement and closing documents to understand which fees they're responsible for paying.
Explore Wisconsin Real Estate Transfer Information →
10. Does Earnest Money Reduce Your Closing Costs?
Earnest money doesn't necessarily reduce the closing costs charged for your transaction.
However, it usually reduces the remaining amount you must bring to closing because it is credited toward your required funds.
Example: $200,000 Home Purchase
Down Payment: $6,000
Closing Costs: $6,000
Total Required Before Adjustments: $12,000
Earnest Money Previously Paid: $2,000
Estimated Remaining Cash Needed: $10,000
This example excludes seller credits, tax prorations, assistance programs, and other adjustments.
The actual amount due will appear in your final closing documents.
11. Can the Seller Pay Some of Your Closing Costs?
Sometimes!
Buyers and sellers may negotiate seller contributions toward eligible closing costs.
These are often called seller concessions or seller credits.
For example, a buyer might request that the seller contribute $5,000 toward qualifying closing expenses.
However, seller concessions are not guaranteed.
The seller must agree, and mortgage program rules may limit the amount or types of expenses that can be covered.
In some situations, a seller may require a higher purchase price in exchange for providing a credit.
That means a seller credit isn't necessarily free money.
Ask your REALTOR® and lender to help you evaluate the total financial impact of the proposed terms.
12. Can Wisconsin Down Payment Assistance Help With Closing Costs?
Possibly!
Some Wisconsin assistance programs may help eligible buyers cover qualifying down payment and closing expenses.
Programs worth exploring include:
- WHEDA mortgage and down payment assistance options
- Eligible local government homebuyer programs
- Qualifying nonprofit assistance programs
- Participating lender assistance programs
Not all assistance is structured as a grant.
Some programs provide second mortgages, deferred-payment loans, or forgivable loans.
Assistance eligibility, funding, and repayment requirements vary.
It's important to confirm program details before relying on assistance to complete your purchase.
Explore WHEDA Homebuyer Assistance →
13. What Is a Loan Estimate?
A Loan Estimate is a standardized document that helps borrowers understand important mortgage terms and estimated costs.
For covered mortgage applications, lenders generally must provide a Loan Estimate within three business days after receiving the required application information.
The document includes information such as:
- Estimated loan amount
- Interest rate
- Monthly principal and interest payment
- Estimated taxes and insurance
- Closing costs
- Estimated cash needed to close
The Loan Estimate makes it easier to compare mortgage offers from different lenders.
However, it is an estimate rather than a guarantee that every cost will remain unchanged.
Some fees are subject to specific limits on changes, while others may vary based on permitted circumstances.
Understand Your Loan Estimate →
14. What Is a Closing Disclosure?
A Closing Disclosure is a document that provides important details about your mortgage and final closing costs.
For most standard mortgage purchases, you must receive the Closing Disclosure at least three business days before closing.
This gives you time to review the information and ask questions.
Important items to check include:
- Loan amount
- Interest rate
- Monthly payment
- Closing costs
- Seller credits
- Earnest money credit
- Property tax adjustments
- Final cash needed to close
Compare your Closing Disclosure with your most recent Loan Estimate.
If something looks incorrect or unexpectedly different, contact your lender or closing professional promptly.
Learn How to Review a Closing Disclosure →
15. What Does Cash to Close Mean?
Your cash to close is the amount you're required to provide at closing after applicable credits and adjustments.
It may account for:
- Your down payment
- Closing costs
- Prepaid expenses
- Initial escrow deposits
- Earnest money already paid
- Seller credits
- Applicable tax prorations
- Other transaction adjustments
The final amount may differ from what you estimated earlier in the process.
Review your closing documents carefully and ask questions before transferring funds.
Important: Protect Yourself From Wire Fraud
Real estate transactions can be targeted by scammers who send fraudulent payment instructions.
Never rely solely on an unexpected email or text message that changes where you should send closing funds.
Before transferring money, independently call your title company or closing professional using a trusted phone number you already verified.
Do not use a new phone number provided only in a suspicious message.
Before wiring closing funds, independently verify payment instructions with your closing professional. A few minutes of verification can help protect your savings.
16. How Can You Reduce Closing Costs?
Depending on your circumstances, there may be several ways to manage closing expenses.
- Compare Loan Estimates from multiple mortgage lenders.
- Ask about lender fees and available loan options.
- Explore eligible WHEDA and local assistance programs.
- Discuss potential seller concessions with your REALTOR®.
- Compare services you are permitted to shop for, such as certain title services.
- Ask your lender to explain discount points and lender credits.
- Review your estimated prepaid expenses and escrow deposits.
- Understand how your closing date may affect prepaid interest.
Some options reduce upfront expenses but may increase your interest rate, loan balance, or long-term borrowing costs.
Compare the full financial picture rather than focusing only on the amount due at closing.
17. Don't Forget About Expenses After Closing
Buying a home involves more than reaching closing day.
Before using all your savings toward the purchase, consider upcoming expenses such as:
- Moving costs
- Utility setup
- Furniture and appliances
- Routine maintenance
- Unexpected repairs
- Property taxes and insurance
- Emergency savings
Keeping some financial reserves can help you manage the responsibilities of homeownership.
Your goal shouldn't simply be to afford closing day. It should be to comfortably afford the home after you move in.
Frequently Asked Questions
How much are closing costs in Wisconsin?
A common planning estimate is approximately 2% to 5% of the purchase price, excluding the down payment. Actual costs vary.
Are closing costs included in my down payment?
No. Closing costs and the down payment are separate components of your home purchase.
Can the seller pay closing costs?
Sometimes. Seller contributions are negotiable and subject to applicable mortgage program limits.
Can closing costs be covered by grants?
Some eligible assistance programs may help with qualifying closing expenses. Program requirements and funding availability vary.
Does earnest money count toward closing?
Earnest money is typically credited toward your required funds at closing, subject to the contract and transaction.
Who pays property taxes at closing in Wisconsin?
Property taxes are commonly prorated between the buyer and seller according to the purchase agreement.
Do I pay my first year's homeowners insurance at closing?
Many mortgage transactions require an upfront homeowners insurance premium. Ask your lender and insurance provider about the amount and timing.
Can I negotiate lender fees?
Some lender charges may be negotiable or may differ between mortgage offers. Compare Loan Estimates and ask lenders to explain their fees.
What happens if my closing costs change?
Contact your lender to understand the reason. Some changes are restricted by federal mortgage disclosure rules, while other costs may vary under permitted circumstances.
How do I know exactly how much money to bring to closing?
Review your Closing Disclosure and confirm the final amount and payment instructions directly with your lender or closing professional.
Continue Your Homebuying Education
Understanding closing costs is an important part of preparing for homeownership! Explore these additional resources to learn how much money you may need, what happens after making an offer, and how to prepare for closing day.
Prepare for Closing With Confidence
Buying a home should be exciting, not full of unexpected financial surprises.
I'm Stephanie Stuart, REALTOR® with Epique Realty and founder of Educate 2 Own.
I help Wisconsin buyers understand the homebuying process, explore available resources, and prepare for the financial responsibilities of ownership.
Whether you're ready to purchase or still researching your options, education is the first step toward making confident decisions.
Let's discuss your goals and create a homebuying plan that works for you.
Educate. Empower. Own. Thrive!
Educational information only. Closing costs, lender fees, tax prorations, mortgage requirements, assistance programs, and contractual responsibilities vary. Consult qualified mortgage, title, real estate, tax, and legal professionals regarding your specific circumstances.
Stephanie Stuart, REALTOR® | Brokered by Epique Realty
Recent Posts