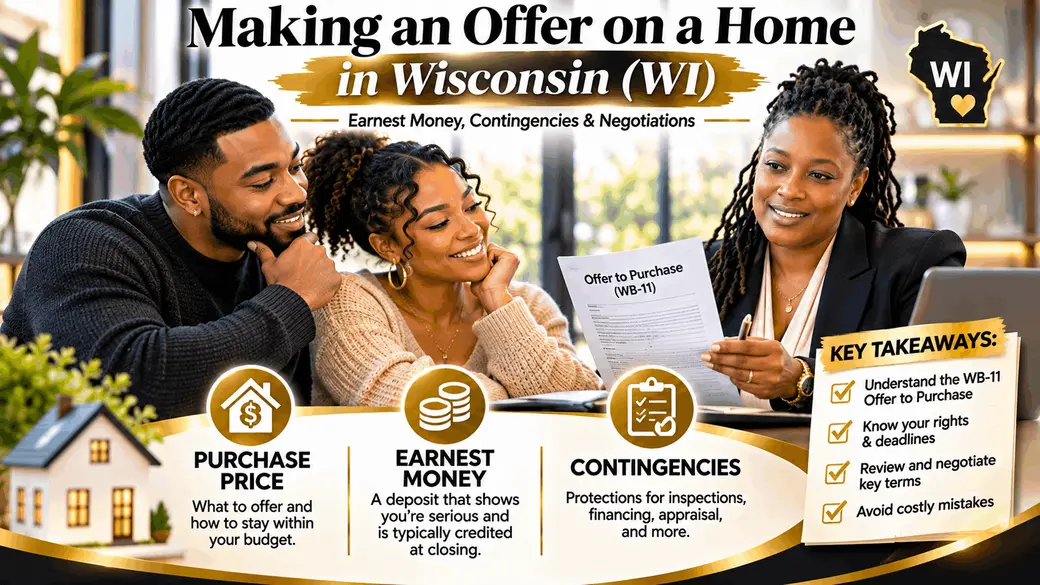
Making an Offer on a House in Wisconsin: Earnest Money, Contingencies & Negotiations
EDUCATE 2 OWN | FIRST-TIME HOMEBUYER SERIES
You Found a House You Love. Now What?
You've toured homes, explored neighborhoods, and finally found a property that feels right for you.
Congratulations! Now comes an exciting and important part of the homebuying process: making an offer.
But before deciding how much you're willing to pay, there are several things you should understand.
Making an offer involves more than choosing a purchase price. Your offer may include earnest money, financing terms, inspection contingencies, deadlines, and other important conditions.
Whether you're purchasing in Milwaukee, West Allis, Wauwatosa, Racine, Madison, or another Wisconsin community, understanding these details can help you make informed decisions.
Let's walk through the process together.
1. What Is an Offer to Purchase?
An Offer to Purchase is a written proposal outlining the terms under which you're willing to purchase a property.
For many residential transactions in Wisconsin, real estate professionals use the WB-11 Residential Offer to Purchase form.
Your offer may include:
- The property's address and legal description
- Your proposed purchase price
- Earnest money arrangements
- Financing terms
- Inspection contingencies
- Appraisal provisions
- Closing date
- Items included or excluded from the sale
- Other negotiated terms and deadlines
Once an offer is properly accepted and delivered in accordance with its terms, it can become a legally binding contract.
Important: Never sign an offer without understanding the terms, deadlines, and potential consequences.
2. How Do You Decide What to Offer?
One of the first questions buyers ask is, "Should I offer the asking price?"
The answer depends on the property and market conditions.
Your REALTOR® can help you evaluate:
- Recent comparable property sales
- The home's condition
- How long the property has been listed
- Current market activity
- The property's features and location
- Potential repair expenses
- Your financing and budget
For example, a property listed at $225,000 isn't automatically worth $225,000 simply because that's the seller's asking price.
Comparable sales and other market information can help you determine whether the asking price appears reasonable.
However, no REALTOR® can guarantee what a seller will accept or what a property will appraise for.
Your offer should reflect the property's value, your financial comfort, and your goals. Winning an accepted offer isn't the goal if the terms put you in an uncomfortable financial position.
3. What Is Earnest Money?
Earnest money is a deposit that demonstrates your commitment to purchasing a property.
It's commonly submitted after an offer is accepted, according to the deadline and terms established in the purchase contract.
The amount is negotiable.
For example, a buyer purchasing a $200,000 property might offer $2,000 in earnest money.
However, there is no universal earnest money amount required for every Wisconsin home purchase.
The appropriate amount depends on the transaction, negotiations, and the buyer's circumstances.
Where Does Earnest Money Go?
Earnest money is generally held by the party designated in the purchase agreement, such as a real estate brokerage or another authorized holder.
When a brokerage holds earnest money, applicable trust-account rules govern how the funds are handled.
If a title company or another party holds the funds, the parties should understand the applicable escrow arrangements.
Does Earnest Money Count Toward Your Purchase?
Generally, yes.
At closing, earnest money is typically credited toward the amount you're required to contribute to the transaction.
It isn't automatically an additional expense on top of your down payment and closing costs.
Example: $200,000 Home Purchase
Purchase Price: $200,000
Illustrative 3% Down Payment: $6,000
Earnest Money Paid: $2,000
Remaining Down Payment: $4,000
The earnest money would typically be credited toward the buyer's required funds at closing.
Closing costs and other adjustments would also affect the final amount due.
This example is for educational purposes only and does not represent a financing quote.
4. Can You Lose Your Earnest Money?
Potentially.
Earnest money is not automatically refundable simply because a buyer changes their mind.
Whether the buyer is entitled to receive earnest money back depends on the purchase contract and the circumstances surrounding the transaction.
For example, certain properly exercised contractual contingencies may provide a basis for terminating an offer.
However, missing deadlines or failing to meet contractual obligations can create serious consequences.
If a transaction doesn't close, the earnest money may need to be distributed according to the agreement, applicable escrow procedures, or other lawful instructions.
Disagreements about earnest money can delay its release.
Before signing: Ask your REALTOR® to explain how earnest money is handled and which circumstances could place your deposit at risk.
5. What Are Contingencies?
A contingency is a contractual condition that must be addressed as described in the purchase agreement.
Contingencies can provide important protections, but they also establish responsibilities and deadlines.
Common contingencies include:
- Home inspection
- Financing commitment
- Appraisal
- Sale or closing of another property
- Other property-specific inspections or testing
Not every offer includes every contingency.
The protections available to a buyer depend on the actual language included in the accepted contract.
6. Understanding the Home Inspection Contingency
A home inspection contingency can provide buyers with an opportunity to have the property inspected and address qualifying concerns according to the contract.
Wisconsin's standard residential offer includes specific procedures concerning inspections, defects, notices, and deadlines.
Depending on the agreement, buyers may be able to obtain:
- A general home inspection
- Inspections of specified property components
- Permitted follow-up inspections
Some specialized testing, such as radon testing, requires separate contractual authorization.
What Happens If the Inspection Finds Problems?
First, review the inspector's written report.
Depending on the findings and your contract, possible next steps may include discussing repairs, proposing an amendment, or following the contractual notice-of-defects procedure.
These are not interchangeable actions.
For example, proposing an amendment asking the seller to repair something is different from delivering a formal Notice of Defects under Wisconsin's inspection contingency.
The seller's right to cure, if included, also affects what happens next.
Important: An inspection contingency doesn't automatically allow a buyer to cancel a contract because they dislike any condition they discover.
Buyers must follow the specific requirements and deadlines established by the agreement.
A home inspection helps you understand what you're purchasing. Before waiving an inspection contingency, make sure you understand the risks and the protections you may be giving up.
7. Understanding the Financing Commitment Contingency
If you're obtaining a mortgage, financing is an important part of your purchase.
A financing commitment contingency generally establishes requirements related to obtaining and delivering a written loan commitment.
In Wisconsin, this contingency is not simply a guarantee that your loan will fund at closing.
Your lender may need to review:
- Income and employment
- Credit information
- Bank statements and available funds
- Property information
- Appraisal results
- Other underwriting requirements
If financing isn't available under the terms addressed by the contract, specific notice and documentation requirements may apply.
Buyers should communicate promptly with their lender and REALTOR® if financing concerns arise.
Remember: Receiving a mortgage preapproval is different from satisfying a financing commitment contingency.
8. What Is an Appraisal Contingency?
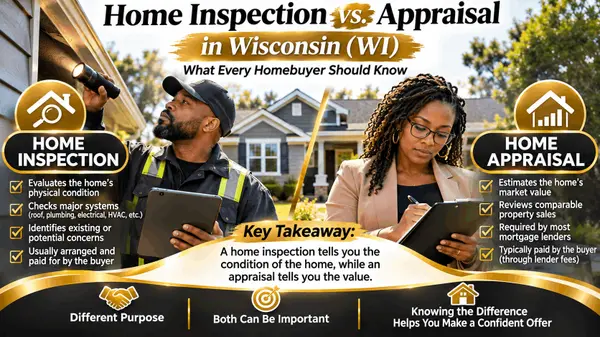
An appraisal is an independent opinion of a property's value prepared by a qualified appraiser.
Mortgage lenders commonly require appraisals to help evaluate the property being financed.
For example:
Accepted Purchase Price: $250,000
Appraised Value: $235,000
Difference: $15,000
When a property appraises below the agreed purchase price, the buyer may need to explore available options.
These could include renegotiating the price, contributing additional funds if financially appropriate, or exercising applicable contractual protections.
However, those options depend on the financing program and purchase agreement.
Having a financing contingency does not automatically mean you have the same protections as a separate appraisal contingency.
Discuss this distinction with your REALTOR® before submitting your offer.
9. Can You Ask the Seller to Pay Closing Costs?
Sometimes!
Buyers may negotiate for the seller to contribute toward certain closing costs.
These contributions are often called seller concessions or seller credits.
For example, a buyer might request that the seller contribute $5,000 toward eligible closing costs.
Whether the seller agrees depends on the negotiations.
The buyer's mortgage program may also limit the amount and types of costs that can be covered.
Seller concessions are not guaranteed, and they don't always reduce the total cost of purchasing a property.
Ask your lender to explain how the proposed contribution would affect your financing.
10. What Happens After You Submit an Offer?
After receiving your offer, the seller generally has several options.
Option 1: Accept the Offer
The seller may accept the offer according to its terms.
When all applicable acceptance and delivery requirements are satisfied, the parties may have a binding purchase agreement.
Option 2: Reject the Offer
The seller may decide not to accept your proposed terms.
This doesn't necessarily mean you made a mistake. The seller may have different pricing expectations or other priorities.
Option 3: Make a Counteroffer
The seller may propose changes to the purchase price, closing date, contingencies, or other terms.
You can then evaluate whether those proposed changes work for you.
A counteroffer is part of the negotiation process, not automatically a rejection of your interest in purchasing the home.
11. Can You Negotiate More Than the Price?
Absolutely!
Real estate negotiations can involve several terms beyond the purchase price.
Depending on the transaction, you may negotiate:
- Closing date
- Earnest money
- Seller contributions toward closing costs
- Items included in the sale
- Inspection provisions
- Repair arrangements
- Occupancy arrangements
- Other contract terms
For example, a seller may value a flexible closing date more than a small increase in purchase price.
Another seller may prefer an offer with fewer conditions.
Understanding the seller's stated priorities can help buyers structure a thoughtful offer.
However, reducing contractual protections can increase your risk.
Make sure you understand the tradeoffs before agreeing to changes.
12. What Happens in a Multiple-Offer Situation?
Sometimes several buyers are interested in the same property.
In a multiple-offer situation, sellers may compare purchase prices, financing arrangements, contingencies, closing dates, and other terms.
There is no guarantee that the highest-priced offer will be accepted.
A seller may consider the overall terms and their individual priorities.
Your REALTOR® can help you understand your options and develop an offer strategy based on available information.
However, the decision about how much to offer and which terms to accept remains yours.
Remember: You should never feel obligated to exceed your comfortable budget simply because other buyers are interested.
13. What Happens Once Your Offer Is Accepted?
Once your offer becomes an accepted contract, the transaction moves into the next stage.
Depending on your agreement, you may need to:
- Submit earnest money by the required deadline.
- Communicate the accepted offer to your lender.
- Schedule authorized inspections.
- Review inspection findings.
- Complete financing-related requirements.
- Respond to requests for additional documentation.
- Monitor contingency deadlines.
- Review your closing documents.
- Complete your final walkthrough when permitted.
- Attend closing and complete the purchase.
Your REALTOR®, lender, and closing professionals can help you understand which requirements apply to your transaction.
Keep a copy of your accepted offer and a written list of important deadlines.
14. Common Mistakes Buyers Should Avoid
When making an offer, try to avoid these common mistakes:
- Offering more than you can comfortably afford
- Signing without understanding the terms
- Assuming earnest money is always refundable
- Waiving contingencies without understanding the risks
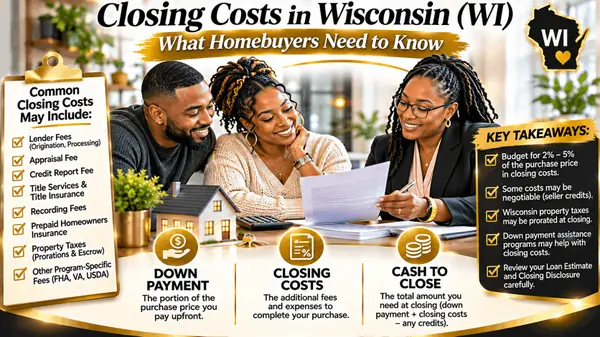
- Forgetting to budget for closing costs
- Ignoring inspection concerns
- Missing contractual deadlines
- Making major financial changes before closing
- Assuming preapproval guarantees final mortgage approval
- Allowing competition to override your financial goals
Buying a home involves important decisions, but you don't need to rush through them without understanding your options.
A successful offer isn't just one the seller accepts. It's one you understand, can financially support, and feel comfortable moving forward with.
Frequently Asked Questions
How much earnest money do I need in Wisconsin?
There is no single earnest money amount required for every Wisconsin transaction. The amount is negotiable and depends on the purchase agreement and circumstances.
Is earnest money refundable?
It depends on the contract and what happens during the transaction. Buyers should never assume their deposit is automatically refundable.
Can I offer less than the asking price?
Yes. Buyers may propose a purchase price below the listing price. Sellers are not required to accept it.
Can I offer more than the asking price?
Yes. However, consider your budget, comparable sales, appraisal considerations, and potential financing consequences.
Do I have to waive the home inspection to compete?
No. Waiving an inspection contingency is a negotiation decision that carries risks. You should understand those risks and available alternatives before deciding.
Can the seller reject my offer?
Yes. Sellers may accept, reject, or counter an offer, subject to their legal and contractual obligations.
Can I cancel an accepted offer?
Sometimes, depending on the agreement and circumstances. An accepted offer is generally binding, and cancellation can have legal and financial consequences.
Does preapproval guarantee my offer will close?
No. Final mortgage approval and closing depend on additional requirements, including underwriting and contractual obligations.
Can I negotiate repairs after an inspection?
Possibly. Buyers and sellers may negotiate changes, but contractual rights and obligations depend on the inspection contingency and agreed terms.
Continue Your Homebuying Education
Making an offer is an exciting milestone, but there's still more to understand before receiving your keys! Explore these resources to learn about inspections, closing expenses, and what happens on closing day.
Make an Offer With Knowledge and Confidence
Finding a home you love is exciting. Understanding the contract you're signing is just as important.
I'm Stephanie Stuart, REALTOR® with Epique Realty and founder of Educate 2 Own.
I help Wisconsin buyers understand the homebuying process, evaluate properties, review their options, and navigate real estate negotiations.
My goal is to help you make informed decisions that support your financial comfort and long-term goals.
Whether you're preparing to submit your first offer or simply learning how the process works, I'm here to help.
LET'S DISCUSS YOUR HOMEBUYING GOALS
Educate. Empower. Own. Thrive!
This article is intended for general educational purposes and does not constitute legal, lending, or financial advice. Contract terms, contingency protections, earnest money procedures, and deadlines depend on the specific transaction. Consult qualified Wisconsin real estate, lending, and legal professionals regarding your circumstances.
Stephanie Stuart, REALTOR® | Brokered by Epique Realty
Recent Posts