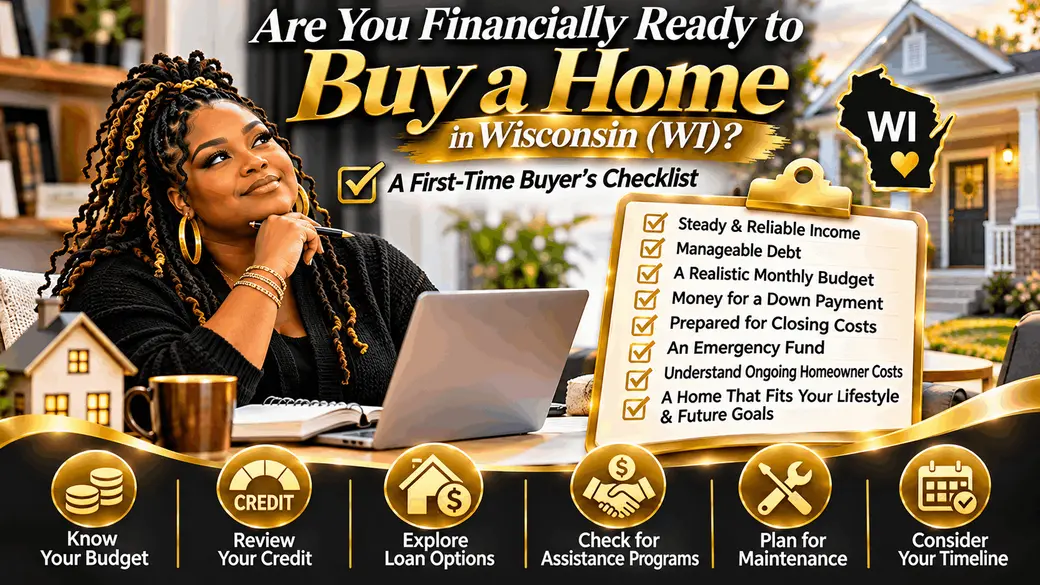
Are You Financially Ready to Buy a Home in Wisconsin? A First-Time Buyer's Checklist
EDUCATE 2 OWN | FIRST-TIME HOMEBUYER SERIES
Are You Ready to Become a Homeowner?
Buying a home is an exciting milestone. It can provide stability, opportunities to build equity, and a place to create lasting memories.
But before scheduling showings or making an offer, there's an important question worth asking:
Am I financially and personally ready for homeownership?
Being approved for a mortgage doesn't automatically mean purchasing a home is the best decision for your circumstances.
Homeownership comes with responsibilities that extend far beyond your monthly mortgage payment.
Whether you're planning to buy in Milwaukee, West Allis, Wauwatosa, Racine, Madison, Green Bay, or another Wisconsin community, understanding your readiness can help you make confident decisions.
Let's explore what you should consider before purchasing your first home.
1. Do You Have Reliable Income?
One of the first things mortgage lenders evaluate is your ability to repay the loan.
They may review your:
- Employment history
- Income documentation
- Existing debts
- Self-employment income, when applicable
- Other qualifying income sources
However, financial readiness involves more than simply meeting a lender's income requirements.
Ask yourself:
- Is my income reasonably predictable?
- Can I comfortably manage my current expenses?
- Do I have a plan if my income decreases?
- Would my housing payment leave room for savings?
Having variable income doesn't automatically prevent you from purchasing a home.
Self-employed individuals, commission-based workers, and other borrowers may qualify under applicable mortgage guidelines.
The important thing is understanding how your income supports your financial responsibilities.
2. Do You Understand Your Monthly Budget?
Before buying a home, review where your money goes each month.
Start with your take-home income and regular expenses.
These might include:
- Transportation
- Groceries
- Childcare
- Insurance
- Debt payments
- Utilities
- Healthcare expenses
- Savings
- Personal and family activities
Now consider how purchasing a home would change those expenses.
Some costs may stay the same, while others may increase.
Your goal is to establish a housing budget that allows you to meet your obligations without constantly worrying about money.
A lender determines how much you may qualify to borrow. You determine how much you're comfortable spending.
3. Do You Know What Your Mortgage Payment Includes?
Your mortgage payment may involve more than principal and interest.
Depending on your loan and property, your total monthly housing payment may include:
- Mortgage principal
- Mortgage interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when required
- Association fees, if applicable
Some expenses may be collected through an escrow account, while others may be paid separately.
You should also budget for utilities, repairs, and routine maintenance.
Remember that property taxes, insurance premiums, and association fees may change over time.
Even with a fixed-rate mortgage, your total monthly housing expenses may increase.
4. How Much Home Can You Comfortably Afford?
Let's look at a simple hypothetical budget.
Example: Monthly Household Budget
Monthly Take-Home Income: $5,000
Existing Living Expenses and Debt Payments: $2,300
Planned Savings: $500
Amount Remaining: $2,200
This leaves $2,200 before accounting for a new housing payment and any housing-related expenses not already included in the budget.
That doesn't automatically mean the household should spend $2,200 on a mortgage.
The buyer must also consider maintenance, utilities, unexpected expenses, and other financial goals.
A more comfortable housing payment may be significantly lower.
The goal is not to spend every available dollar. The goal is to create a sustainable financial plan.
5. Do You Have Money Saved for a Down Payment?
Many buyers believe they need 20% down to purchase a home.
That's not necessarily true.
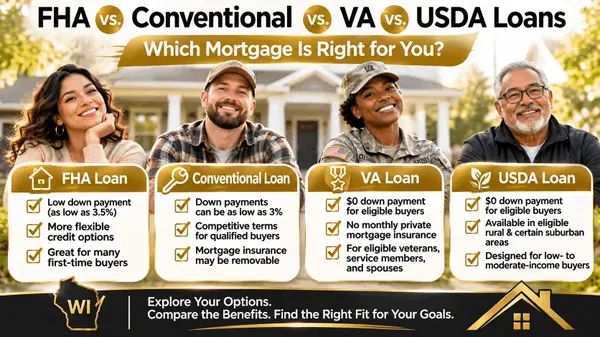
Depending on eligibility, some mortgage programs offer:
- Conventional financing with as little as 3% down
- FHA financing with as little as 3.5% down
- VA financing with no down payment required for certain eligible borrowers
- USDA financing with no down payment for eligible buyers and properties
However, a smaller down payment may increase your monthly payment or other borrowing costs.
Ask a mortgage lender to compare the financing options available to you.
Remember that down payment assistance may also be available to qualifying Wisconsin buyers.
6. Have You Prepared for Closing Costs?
Your down payment isn't the only expense involved in purchasing a home.
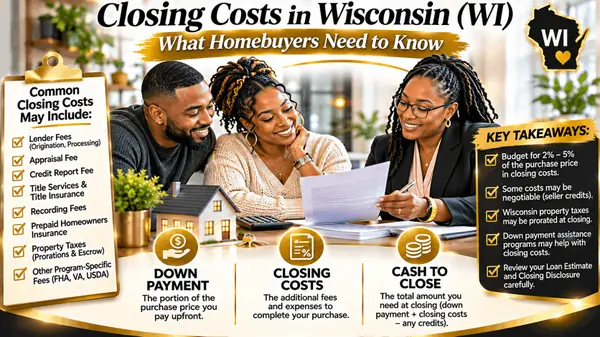
Closing costs may include:
- Mortgage lender fees
- Appraisal charges
- Title services
- Recording fees
- Prepaid homeowners insurance
- Property tax adjustments
- Initial escrow deposits
Closing costs commonly range from approximately 2% to 5% of the purchase price, excluding your down payment.
Actual costs vary based on the mortgage, property, lender, and transaction.
Example: $200,000 Home
Illustrative 3% Down Payment: $6,000
Illustrative 3% Closing Costs: $6,000
Estimated Total Before Credits: $12,000
This simplified example excludes other expenses and transaction-specific adjustments.
Assistance programs, seller credits, and earnest money may affect how much cash you need at closing.
Request a personalized estimate from your mortgage lender.
7. Do You Have an Emergency Fund?
One of the biggest differences between renting and owning is responsibility for unexpected property expenses.
Imagine purchasing your first home and discovering that the furnace needs an expensive repair during a Wisconsin winter.
Or perhaps your refrigerator stops working, the basement experiences water intrusion, or your vehicle needs repairs.
These expenses can quickly affect your finances.
Maintaining emergency savings can help you prepare.
A commonly suggested starting point is enough savings to cover three to six months of essential expenses, although the appropriate amount depends on your circumstances.
If that amount isn't realistic immediately, you can begin building savings gradually.
Ask yourself:
- Could I handle an unexpected $1,000 expense?
- What would happen if I temporarily lost income?
- Could I afford an urgent home repair?
- Would purchasing this home use all my savings?
There's no single emergency fund amount that guarantees financial security.
However, keeping money available for unexpected expenses can make homeownership more manageable.
Learn More About Preparing Your Savings →
8. Are You Comfortable With Your Current Debt?
Having debt doesn't automatically mean you aren't ready to buy a home.
Many homeowners have car payments, student loans, credit cards, or other financial obligations.
Mortgage lenders commonly evaluate your debt-to-income ratio, also called DTI.
This compares certain qualifying monthly debt obligations with your gross monthly income.
However, your personal budget should also account for expenses that may not be included in the lender's DTI calculation.
For example, childcare, groceries, transportation, and other household expenses can significantly affect affordability.
Ask yourself whether adding a mortgage would leave enough room for your existing responsibilities.
If your debt payments already create financial stress, reducing those obligations before purchasing may be worth considering.
9. Have You Reviewed Your Credit?
Your credit history can influence your mortgage eligibility, interest rate, and financing options.
Before applying for a mortgage, consider reviewing your credit reports for inaccurate information.
You can obtain free credit reports through the federally authorized website:
Visit AnnualCreditReport.com →
Look for:
- Incorrect account information
- Payments mistakenly reported as late
- Accounts you don't recognize
- Incorrect balances
- Other reporting errors
If your credit needs improvement, consider developing a plan to make payments consistently, reduce revolving debt, and correct legitimate reporting errors.
You don't need perfect credit to begin exploring homeownership.
However, understanding your credit profile can help you prepare.
10. Are You Prepared for Home Maintenance?
Homeownership comes with ongoing maintenance responsibilities.
When you're renting, certain repairs may be handled by your landlord.
When you own the property, you're generally responsible for maintaining it.
Depending on your home, this may involve:
- Heating and cooling maintenance
- Plumbing repairs
- Roof upkeep
- Appliance replacement
- Exterior maintenance
- Snow removal
- Lawn care
- Gutter cleaning
- Other property repairs
Wisconsin's seasonal weather can add important maintenance considerations.
For example, you may need to prepare your home for freezing temperatures, snow accumulation, and spring drainage.
Before purchasing, consider whether you have the time, financial resources, or professional support to maintain the property.
You don't have to know how to perform every repair yourself.
However, you should be prepared to arrange and pay for maintenance when needed.
11. Have You Considered Your Lifestyle and Future Plans?
Financial readiness isn't the only consideration when purchasing a home.
Your lifestyle and plans matter too.
Think about:
- Your preferred community
- Commute and transportation
- Household space requirements
- Accessibility needs
- Desired maintenance responsibilities
- Potential employment changes
- Future household changes
- How long you expect to own the property
Buying and selling real estate involves expenses.
If you expect to relocate soon, purchasing may or may not make financial sense depending on market conditions and your circumstances.
Consider whether the property fits both your current needs and your anticipated future plans.
12. Have You Compared Renting vs. Buying?
Renting isn't automatically a poor financial decision.
And buying isn't automatically the right decision for everyone.
Renting may offer certain advantages, including:
- Greater flexibility to relocate
- Fewer direct property maintenance responsibilities
- Potentially lower upfront costs
- Less exposure to property value fluctuations
Homeownership may offer different opportunities, including:
- Building equity through mortgage principal reduction
- Greater control over certain property decisions
- Potential property appreciation
- Long-term housing stability
- Opportunities to customize your living space
However, property values can decline, and homeowners remain responsible for ongoing property expenses.
The financial benefits of buying also depend on how long you own the property, financing costs, and market conditions.
Compare your options based on your actual expenses and goals.
13. Are You Buying Because You're Ready or Because You Feel Pressured?
This question deserves attention.
Sometimes people feel pressure to purchase because:
- Friends or relatives recently bought homes
- They're tired of paying rent
- They believe prices will always increase
- They've received mortgage preapproval
- Someone told them they're missing an opportunity
- They feel they should own a home by a certain age
But buying a home shouldn't be based solely on someone else's expectations.
You should understand the financial commitment and feel comfortable moving forward.
If you need more time to save money, improve credit, compare neighborhoods, or evaluate your goals, that's okay.
Homeownership is not a race. Buying when you're financially prepared can be more important than buying quickly.
14. What If You're Not Ready to Buy Today?
Not being ready today doesn't mean you can't become a homeowner in the future.
Sometimes the best first step is developing a realistic preparation plan.
If You Want to Buy Within 3 Months
Consider focusing on:
- Reviewing your current finances
- Speaking with mortgage lenders
- Comparing financing options
- Confirming available savings
- Learning about the homebuying process
If You Want to Buy Within 6–12 Months
You may have additional time to:
- Build savings
- Reduce debt
- Review credit reports
- Research neighborhoods
- Explore down payment assistance programs
If You Want to Buy Within 1–3 Years
Consider using this time to:
- Establish consistent savings habits
- Improve your financial stability
- Research mortgage programs
- Learn about property maintenance
- Develop long-term financial goals
These timelines are planning examples, not guarantees of mortgage qualification.
Everyone's financial circumstances are different.
15. Could Wisconsin Homebuyer Assistance Help?
Some Wisconsin buyers may qualify for financing programs or assistance that helps reduce upfront homebuying expenses.
Resources worth exploring include:
- WHEDA mortgage programs
- WHEDA down payment assistance
- Eligible municipal assistance programs
- Participating lender assistance programs
- Approved nonprofit homebuyer resources
Program requirements may involve income, credit, property type, occupancy, education, and other eligibility criteria.
Assistance isn't always free money.
Some programs involve second mortgages, repayment conditions, or forgiveness requirements.
Before relying on assistance, confirm current eligibility and funding availability.
Explore Wisconsin Homebuyer Programs →
16. Your Financial Readiness Checklist
Use this checklist to evaluate your current preparation for homeownership.
Income and Budget
- I understand my monthly take-home income.
- I've reviewed my regular expenses.
- I know how much I can comfortably spend on housing.
- I have a plan for unexpected income changes.
Credit and Debt
- I've reviewed my credit reports.
- I understand my existing debt obligations.
- I've explored my potential mortgage options.
- I'm comfortable with my current debt payments.
Savings
- I've estimated my potential down payment.
- I understand that closing costs are separate.
- I've considered moving expenses.
- I have or am building emergency savings.
Homeownership Responsibilities
- I understand that property taxes can change.
- I've considered homeowners insurance costs.
- I'm prepared for routine maintenance.
- I understand that unexpected repairs may occur.
Personal Readiness
- I've considered my future plans.
- I've researched the communities that interest me.
- I understand the difference between renting and owning.
- I'm making this decision because it supports my goals.
You don't need to check every box before asking questions about homeownership.
Use this checklist to identify areas where additional preparation may be helpful.
17. Three Possible Next Steps
After reviewing your finances and goals, you may discover that you're ready to move forward, almost ready, or need more preparation time.
Option 1: You're Ready to Explore Buying
If your budget, savings, and circumstances support purchasing, consider speaking with mortgage lenders and a real estate professional.
Learn about available financing options and establish a comfortable purchase range.
Option 2: You're Almost Ready
Maybe you want to save more money, reduce a debt balance, or better understand your mortgage options.
Developing a short-term preparation plan may help you move forward with greater confidence.
Option 3: You're Planning for the Future
Maybe purchasing isn't the right decision this year.
That's okay!
Use this time to learn, save, and prepare for future opportunities.
There is value in making a thoughtful decision rather than rushing into a financial commitment.
Frequently Asked Questions
How do I know if I'm financially ready to buy a house?
Review your income, monthly expenses, savings, debts, emergency reserves, and anticipated homeownership costs. Financial readiness involves both mortgage eligibility and your personal financial comfort.
Do I need to be debt-free before buying?
No. Many mortgage borrowers have existing debts. Lenders evaluate qualifying debt obligations alongside income and other financial factors.
How much should I have in emergency savings?
A commonly recommended goal is three to six months of essential expenses, although your needs may differ based on income stability, property condition, and household responsibilities.
Can I buy a home with less than 20% down?
Yes. Several mortgage programs allow eligible buyers to purchase with smaller down payments.
Should I spend my maximum preapproval amount?
Not necessarily. Choose a payment that fits your personal budget and allows room for savings and other expenses.
Is buying always better than renting?
No. Buying and renting have different costs, responsibilities, and benefits. The right choice depends on your circumstances and goals.
Can I buy a home if my income varies?
Possibly. Mortgage programs may accommodate qualifying self-employment, commission-based, or other variable income when documentation and underwriting requirements are met.
What if I don't have enough money saved?
Consider reviewing your budget, establishing a savings plan, and researching eligible homebuyer assistance programs.
Can I start working with a REALTOR® before I'm ready to purchase?
Absolutely! An educational consultation can help you understand the process, research available resources, and identify practical next steps.
What if I decide to wait another year?
Waiting may be appropriate if you need more financial preparation or expect significant changes in your circumstances. There is no universal deadline for becoming a homeowner.
Continue Your Homebuying Education
Your homeownership journey doesn't end here! Explore these additional Educate 2 Own resources to help you make informed decisions.
Your Homeownership Journey Starts With a Plan
You don't have to be ready to purchase today to begin preparing for tomorrow.
I'm Stephanie Stuart, REALTOR® with Epique Realty and founder of Educate 2 Own.
My mission is to help individuals and families understand real estate, explore opportunities, and make informed decisions that support long-term financial stability.
Whether you're ready to purchase your first home, planning for next year, or simply wondering where to begin, I'm here to help you understand your options.
Let's create a plan that reflects your goals, your finances, and your timeline.
EXPLORE YOUR PATH TO HOMEOWNERSHIP
Educate. Empower. Own. Thrive!
This article is intended for general educational purposes and does not constitute mortgage lending, financial, tax, or legal advice. Mortgage requirements, assistance programs, closing expenses, and financial circumstances vary. Consult qualified lending, financial, real estate, or legal professionals regarding your individual situation.
Stephanie Stuart, REALTOR® | Brokered by Epique Realty
Recent Posts