Prequalification vs. Preapproval: What Wisconsin Homebuyers Need to Know
EDUCATE 2 OWN | FIRST-TIME HOMEBUYER SERIES
Prequalified or Preapproved? Let's Clear Up the Confusion!
You've decided to explore homeownership. Congratulations!
One of the first things you'll hear is that you should get preapproved for a mortgage.
But what exactly does that mean? And is it the same as being prequalified?
Although the terms sound similar, they can represent different levels of financial review.
Understanding the difference can help you prepare for homeownership with confidence.
1. What Is Mortgage Prequalification?
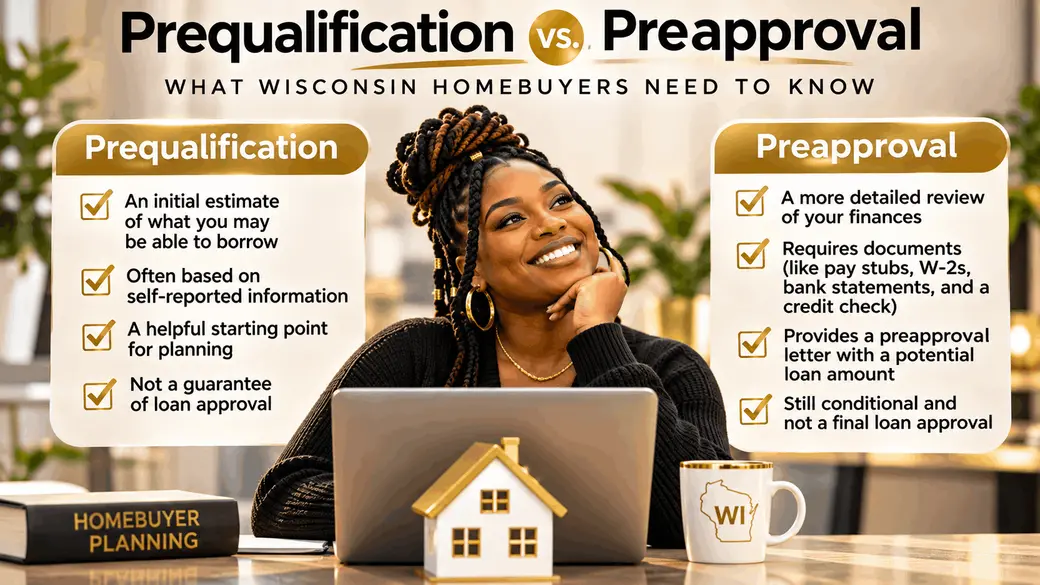
Prequalification is often an early conversation with a lender to estimate how much you may be able to borrow.
A lender may ask about:
- Your income and employment
- Monthly debts
- Credit history
- Savings and available funds
- Your anticipated down payment
Depending on the lender, this information may be self-reported or supported by financial documentation.
Prequalification can be a helpful starting point, especially if you're researching whether homeownership is financially realistic.
Important: Prequalification does not guarantee mortgage approval.
2. What Is Mortgage Preapproval?
Preapproval generally involves a more detailed review of your financial circumstances.
A lender may request:
- Recent pay stubs
- W-2 forms or tax returns
- Bank statements
- Employment information
- Credit authorization
- Documentation of other income or assets
After reviewing your information, the lender may issue a preapproval letter identifying a potential mortgage amount.
This helps you understand your estimated buying power and demonstrates to sellers that you've taken steps toward obtaining financing.
However, preapproval is still conditional.
Final mortgage approval depends on additional factors, including the property, underwriting, and verification of your financial circumstances.
A preapproval is a financial planning tool, not a commitment to purchase a home. You control when you're ready to move forward.
3. What's the Difference?
Prequalification: Often provides an initial estimate based on preliminary financial information.
Preapproval: Generally involves a more detailed evaluation of your finances and potential mortgage eligibility.
Because lenders use these terms differently, it's important to ask exactly what information was reviewed.
Neither guarantees final loan approval.
4. Does Getting Preapproved Affect Your Credit?
It can.
Some lenders use a hard credit inquiry during the preapproval process. Others may offer an initial review using a soft inquiry.
A hard inquiry may temporarily affect your credit score.
However, credit-scoring models generally recognize mortgage rate shopping. Multiple mortgage inquiries made within an applicable shopping window may be treated as one inquiry.
The window varies depending on the scoring model.
Before applying, ask your lender whether a hard credit inquiry is required.
5. How Long Does Preapproval Last?
Many preapproval letters remain valid for approximately 30 to 90 days, although expiration periods vary by lender.
If your preapproval expires, you may need to provide updated financial information.
Your lender might request new pay stubs, bank statements, or another credit review.
Here's the good news: An expired preapproval doesn't mean you can no longer purchase a home.
It simply means your lender may need to reevaluate your eligibility.
6. Does Preapproval Mean You Have to Buy Immediately?
Absolutely not!
One of the biggest misconceptions about preapproval is that buyers must immediately begin looking for homes.
That's not true.
Some buyers get preapproved and find their dream home within weeks.
Others decide to spend additional months saving money, researching neighborhoods, or improving their financial circumstances.
Both approaches are perfectly reasonable.
Your homeownership timeline should reflect your personal goals, financial comfort, and readiness.
You are in control of your homebuying journey. Never feel pressured to purchase a property, accept financing terms, or make decisions you don't fully understand.
7. Should You Speak With More Than One Mortgage Lender?
Yes!
Comparing lenders can help you understand your financing options and potentially save money.
Different lenders may offer different:
- Interest rates
- Closing costs
- Loan programs
- Mortgage insurance options
- Down payment assistance opportunities
- Customer service experiences
Consider speaking with at least three lenders before making your final decision.
When you're ready to compare actual loan offers, request Loan Estimates and review the terms carefully.
8. Mortgage Professionals You Can Connect With
Not sure where to begin?
Finding the right mortgage professional is an important step toward homeownership.
Below are three mortgage professionals you can contact to discuss financing options, ask questions, and learn more about the preapproval process.
Karen Wedvick
Wintrust Mortgage
Senior Mortgage Consultant
NMLS #770831
Connect with Karen to explore mortgage financing, qualification requirements, and available loan programs.
Nathan Julius
Churchill Mortgage
Home Loan Specialist
NMLS #2613390
Connect with Nathan to discuss home financing, mortgage qualifications, and loan options, including programs for eligible first-time buyers.
Jill Nguyen
PrimeLending
Associate Loan Originator
NMLS #2799788
Connect with Jill to discuss mortgage financing, available loan programs, and the steps involved in preparing for homeownership.
You have the freedom to choose your mortgage lender. Consider speaking with multiple professionals, comparing loan options, and reviewing estimated costs before making your decision.
These mortgage professionals are provided as resources for your consideration. You are not required to use any particular lender to work with Educate 2 Own or Stephanie Stuart. Loan approval and program eligibility are determined by the lender.
9. What Happens After You're Preapproved?
Once you're preapproved, you can begin exploring homes that align with your goals and financial comfort level.
Your REALTOR® can help you:
- Understand local housing markets
- Identify properties that fit your needs
- Research neighborhoods
- Evaluate comparable home sales
- Understand the offer process
- Prepare for inspections and closing
Remember, just because you're approved for a certain amount doesn't mean you need to spend that amount.
Choose a monthly payment that supports your lifestyle and financial goals.
Frequently Asked Questions
Can I look at homes before getting preapproved?
Yes. However, preapproval can help you establish a realistic budget and strengthen your position when making an offer.
Is preapproval free?
Some lenders offer preapproval without a fee. Others may charge for certain services. Ask about costs before applying.
Can I get preapproved with imperfect credit?
Possibly. Mortgage qualification requirements vary depending on the lender and loan program.
Can I change lenders after getting preapproved?
Generally, yes. A preapproval doesn't automatically commit you to using that lender. However, changing lenders after entering a purchase contract can affect your closing timeline.
What happens if my income changes after preapproval?
Notify your lender. Changes in income, employment, debts, or other financial circumstances may affect your eligibility.
Continue Your Homebuying Education
Understanding mortgage preapproval is an important step toward homeownership! Explore these additional Educate 2 Own resources to help you prepare for what's next.
Your Homeownership Journey. Your Timeline.
Buying a home is a major financial decision, and you deserve to understand every step.
I'm Stephanie Stuart, REALTOR® with Epique Realty and founder of Educate 2 Own.
I help Wisconsin buyers explore their options, connect with mortgage professionals, and make confident real estate decisions without unnecessary pressure.
Whether you're ready today or preparing for the future, let's create a plan that works for you.
EXPLORE YOUR HOMEBUYING OPTIONS
Educate. Empower. Own. Thrive!
Educational information only. Mortgage requirements, credit inquiries, loan programs, and eligibility guidelines vary. Consult qualified mortgage professionals for guidance specific to your circumstances.
Stephanie Stuart, REALTOR® | Brokered by Epique Realty
Recent Posts